
My Card Wallet
- Rating
- 4.7
- Downloads
- 1.00M
- Content Rating
- Everyone
My Card Wallet - Screenshots
Pros
- Stores multiple loyalty cards in one convenient digital wallet.
- Quickly find cards using search and organized categories.
- Reduces the need to carry bulky physical cards when shopping.
- Card details remain available even when internet access is limited.
- Simple interface makes adding and viewing cards easy for most users.
Cons
- Some stores may not accept digital cards or scanned barcodes.
- You may need to enter card details manually during initial setup.
- Device loss can make your cards temporarily inaccessible.
- Privacy concerns may arise when storing membership data in one app.
- Compatibility with unusual barcode formats may vary by retailer.
My Card Wallet - Description
- App Name
- My Card Wallet
- Package Name
- com.blackhawk.myprepaidcenter
- Developer
- Blackhawk Network
- Category
- Finance
- Last Updated
- Mar 7, 2018
- Version
- 7.3.3.g
I found My Card Wallet most useful when I treated it as a focused control panel for prepaid cards rather than as a complete banking app. Its job is narrow, but that narrowness is also its main strength: it brings prepaid-card management into one place and can add eligible cards to Google Wallet or Samsung Wallet. If you regularly carry prepaid cards, that can remove a surprising amount of small daily friction. If you want budgeting, bank transfers, bill payments, or broad money-management tools, I would look elsewhere.
My overall view is positive because the app stays close to a practical problem. Instead of making me search through messages, physical cards, or separate payment apps, it gives the card relationship a dedicated home. The experience is especially appealing for someone who uses prepaid cards for planned spending, gifts, household purchases, or a controlled travel budget. It is free, rated for Everyone, and developed by Blackhawk Network, the company behind the service.
What My Card Wallet does well in everyday use
The most convincing part of the app is the way it turns a prepaid card from a temporary object into something easier to keep track of. A physical card can be misplaced, forgotten in a drawer, or left out of a mobile-payment routine. Having a central app for managing cards gives me a clearer starting point whenever I want to check what I have available or decide which card to use.
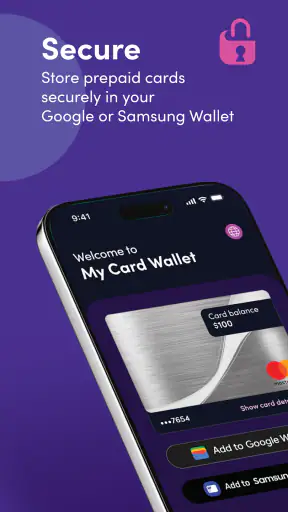
The wallet connection is the feature that makes the app feel more useful than a simple card-notes screen. When a supported card can be added to Google Wallet or Samsung Wallet, it becomes easier to use the card from the phone instead of reaching for plastic. That matters most in ordinary moments: paying at a shop when I have left my physical wallet at home, or keeping several prepaid cards available without carrying all of them.
I would still think of this as a companion to those mobile wallets, not a replacement for them. Google Wallet and Samsung Wallet are designed to hold many kinds of payment cards and passes, while My Card Wallet is centered on prepaid-card management. The practical workflow is therefore different: I would use this app to organize and manage the prepaid side, then use the appropriate mobile wallet at checkout when the card is eligible.
That separation is a useful distinction. Someone who already has a normal bank card in a mobile wallet may not need another app for that card. Someone with prepaid cards, however, may appreciate having a dedicated place to deal with them before moving the usable card into a familiar tap-to-pay environment.
A realistic household scenario
Imagine receiving a prepaid card for a specific purpose and wanting to keep it separate from everyday spending. I could add it to My Card Wallet, check it before shopping, and, if supported, place it in Google Wallet or Samsung Wallet for the actual purchase. That creates a simple boundary: the prepaid balance is the amount available for that purpose, while my main bank account remains untouched.
This is also useful for shared household planning, although I would be careful about treating the app as a shared account-management system. A person might use a prepaid card for school supplies, a gift, or a one-off home project and keep the card details organized on their own phone. The benefit is not sophisticated collaboration; it is reducing the chance of forgetting where the card is or mixing it up with another payment method.
Another less obvious use is temporary spending discipline. A prepaid card can act as a physical limit for a particular activity, and the app makes that card easier to keep in view. I would not call this a full budgeting method, because the app is not a substitute for a budget planner or bank account dashboard. Still, separating a defined spending amount from normal funds can be helpful for people who prefer a concrete limit rather than an abstract category in a finance app.
Why the focused design matters
Finance apps often try to combine accounts, investments, credit monitoring, payments, rewards, and budgeting. That can be convenient, but it can also make a small task feel buried. My Card Wallet has a clearer purpose. I open it because I want to deal with a prepaid card, not because I want a complete picture of my financial life.
That focus may be particularly comfortable for casual users. The age rating is Everyone, and the app is free to install, so there is little barrier to trying it with a compatible prepaid card. I would not expect a learning curve comparable to a full personal-finance platform. The value comes from the direct route between opening the app and handling the card.
Its public reception supports that impression without making the decision automatic. The app has a 4.7 average from around 18 thousand ratings, with roughly 1.4 thousand written reviews, and it has passed one million installs. Those figures suggest that many people find the basic concept worthwhile, but they do not guarantee that every prepaid card or every phone setup will behave identically. Compatibility remains the key question for an individual user.
The mobile-wallet workflow has a practical trade-off
Adding a card to Google Wallet or Samsung Wallet is convenient, but it also means the best payment experience may involve two apps rather than one. I would begin in My Card Wallet to manage the prepaid card, then rely on the phone’s chosen payment wallet for everyday use. That is not a serious problem, but it is worth understanding before installing the app: the dedicated app helps prepare and manage the card, while the platform wallet is usually where the payment interaction happens.
This two-step arrangement can actually be useful if I want to keep the prepaid-card management separate from my other payment cards. It can also feel unnecessary if I only have one card and already know how to manage it through the phone’s wallet. The app earns its place when the dedicated organization is valuable, not simply because another wallet exists.
Where the experience is less convincing
The biggest limitation is the app’s narrow scope. My Card Wallet is not the right choice for someone searching for a complete finance center. I would not install it expecting bank-account aggregation, detailed spending charts, bill scheduling, investment tracking, or a replacement for a traditional banking app. Its purpose is prepaid-card management, and judging it by broader finance-app standards would lead to disappointment.
There is also an important compatibility trade-off around mobile wallets. The ability to add a card to Google Wallet or Samsung Wallet sounds highly convenient, but it depends on the card being eligible and on the relevant phone and wallet setup. I would check the card’s support before building an entire payment routine around the feature. A prepaid card that cannot be added still may be manageable in the app, but the tap-to-pay advantage would not be available in that case.
That uncertainty affects how I would use it in a time-sensitive situation. If I were standing at a checkout and relying on a newly added card, I would not wait until the last second to discover that the card could not be transferred to my preferred wallet. My practical tip is to set up the card at home, while I have time to test the process, and keep the physical card available until I know the phone-based method works.
The app also should not be treated as a guarantee that every prepaid-card task will happen instantly or identically. Card services can have their own rules, activation steps, or usage conditions. My Card Wallet can make the management side more convenient, but it does not erase the underlying differences between prepaid products. I would still read the information attached to the card and keep any important details accessible.
Who may find it unnecessary
If I only use one prepaid card once and do not need it on my phone, the app may add another step rather than remove one. A physical card can be simpler for a single purchase, especially when I do not need mobile-wallet support. Likewise, people who already manage all their eligible cards comfortably through Google Wallet or Samsung Wallet may not gain enough from a separate prepaid-focused app.
I would also skip it if my main goal is detailed financial analysis. A budgeting app or bank application is better suited to tracking recurring expenses, comparing categories, and reviewing a wider financial picture. My Card Wallet is more like a specialized tool in a finance drawer: useful for the right object, but not intended to replace every other tool.
Another consideration is phone compatibility. The current version is 7.3.3.g and requires at least iOS or Android version 11, so I would check the operating system before planning around it. For users on older devices, that requirement can be a practical stop sign rather than a minor detail. On a supported phone, the app is easier to consider; on an unsupported one, the mobile-wallet workflow is irrelevant.
Small habits that make it more useful
I would start by adding cards before I need them. This gives me time to identify which card is which and to test whether Google Wallet or Samsung Wallet accepts it. It also avoids the common mistake of assuming that a card will be ready for mobile payment simply because the app can display or manage it.
For several cards, I would adopt a simple naming habit in my own routine, such as associating each card with its purpose rather than relying only on the plastic design. That is especially helpful when cards look similar or when one is reserved for a particular purchase. The app’s real organizational value appears when I use it consistently, not when I open it only after losing track of a card.
I would also keep a physical backup for important purchases. Mobile payment is convenient, but a phone battery, device setting, or wallet compatibility issue can interrupt the plan. My Card Wallet reduces dependence on carrying every card, but it does not make the physical card useless. For travel or a larger planned purchase, I would carry the card or another accepted payment method as a fallback.
Finally, I would separate “card management” from “balance planning.” The app can be part of a spending routine, but I would use a separate note, budget tool, or personal system if I needed to plan several future expenses. This division keeps expectations realistic and prevents the app from being blamed for not offering functions outside its purpose.
How it compares with familiar alternatives
Compared with a general banking app, My Card Wallet is more specialized and potentially less cluttered for prepaid cards, but it offers a much smaller financial picture. A bank app is better when I need account history, transfers, or broader money movement. My Card Wallet is better when the problem is keeping prepaid cards organized and ready for use.
Compared with Google Wallet or Samsung Wallet alone, it provides a prepaid-focused management layer rather than a broad payment container. The platform wallets are usually the more natural place to pay, while this app is useful for the prepaid-card side of the workflow. If I already have a simple, reliable system for handling prepaid cards, the extra layer may not be worth it. If I regularly use several prepaid cards, the separation can be worthwhile.
Compared with doing everything manually, the app has a clear convenience advantage. Searching through a drawer or relying on memory is easy to underestimate until a card is needed quickly. The trade-off is that I must maintain another app and confirm compatibility before depending on mobile payment. For occasional users, manual handling may remain perfectly adequate; for repeat users, the dedicated organization is more persuasive.
Who I would recommend it to
I would recommend My Card Wallet to people who use prepaid cards often enough that finding, remembering, and using them has become annoying. It is a good fit for someone who wants a free, focused finance app and likes the idea of moving eligible prepaid cards into Google Wallet or Samsung Wallet. It can also suit users who prefer keeping prepaid spending distinct from their primary bank cards.
I would be more cautious recommending it to someone who wants a complete budgeting system, depends on one-time card use, or has an older phone below the required operating-system level. I would also ask whether that person’s cards are eligible for the mobile-wallet feature. If the answer is no and there is no need for dedicated management, the app’s main advantage becomes smaller.
Blackhawk Network has kept the product centered on a recognizable need, and that clarity is reflected in its strong average rating and broad install base. Still, I would choose it for the workflow, not for the numbers. The important test is personal: do prepaid cards form a regular part of your spending, and would having them organized on your phone make your day easier?
My final verdict
My Card Wallet is a useful specialist rather than an all-purpose finance solution. I like it because it addresses prepaid-card organization directly and connects that management task with Google Wallet or Samsung Wallet when the card is supported. In my experience, that combination can make prepaid spending feel less scattered and more convenient.
The limitations are equally clear. It cannot replace a banking app or a serious budgeting tool, and the mobile-payment workflow should be tested before it becomes the only plan. Users with one occasional card may find the app unnecessary, while regular prepaid-card users are more likely to appreciate its focused design.
My recommendation is simple: install it if prepaid cards are a recurring part of your everyday spending and you want a dedicated phone-based workflow. For everyone else, the usual mobile wallet or banking app may be enough. As a free finance app from Blackhawk Network, with an Everyone rating and support for devices running iOS or Android version 11 and newer, it is easy to try—but its real value depends on whether its specialized job matches the way you actually pay.
FAQ
What is My Card Wallet and what can I use it for?
My Card Wallet is a digital wallet app designed to help you keep important cards and card details organized in one place. Depending on the version and platform, it may support loyalty cards, membership cards, gift cards, tickets, or other scannable passes. It is useful for reducing the number of physical cards in your wallet, although supported card types and features can vary by device and region.
Is My Card Wallet safe for storing my cards and personal information?
Before adding sensitive information, review the app’s privacy policy, permissions, and security options. A wallet app may store card data locally, synchronize it through an account, or use third-party services, depending on its configuration. Avoid entering banking passwords, payment-card PINs, or highly confidential information unless the app clearly explains how that data is encrypted and protected.
Can My Card Wallet replace Google Wallet or Apple Wallet for payments?
My Card Wallet should not automatically be considered a replacement for Google Wallet or Apple Wallet. Its main purpose may be organizing cards, passes, and barcodes rather than processing contactless payments. Payment support depends on the app, your smartphone’s NFC capabilities, the card issuer, and local availability. Check the current feature list before expecting tap-to-pay functionality.
How do I add a card to My Card Wallet?
The usual process involves opening My Card Wallet, choosing an option such as Add Card, selecting the appropriate card category, and scanning a barcode or entering the details manually. Some cards may require a photo, card number, expiration date, or membership identifier. Test the displayed barcode at the relevant store or venue after saving it to confirm that it scans correctly.
What happens if I change phones or lose access to my device?
Your cards may not automatically transfer to a new phone unless My Card Wallet provides account synchronization, cloud backup, or an export feature. Before changing devices, check the app’s backup and restore settings and keep important membership numbers available elsewhere. If the phone is lost, use your device’s screen lock and remote security tools, and contact card providers if any sensitive information was stored.


